Pulling Equity from a Greenwich Home
Russell Pruner | November 6, 2026
Blog
Russell Pruner | November 6, 2026
Blog
Greenwich, CT real estate owners who have held their homes for years often have built up considerable equity, and there are four main ways to use it without selling. Equity is what your home is worth minus what you still owe. If you need money for repairs or other expenses, the right choice depends on your current mortgage rate, how much you need, and how long you plan to stay. The numbers here are general, and what they mean for your home is a different question, so call me and I will walk through it with you.
A home equity loan and a HELOC are both second mortgages. They let you keep your primary mortgage, but the combined mortgage debt typically cannot exceed 80% of the home's appraised value.
Here is a simple illustration, not a quote. If a home appraises at $2,000,000, 80% is $1,600,000. If you still owe $600,000, the room left under that limit is about $1,000,000. Your lender sets the actual limit, and your appraisal sets the starting point.
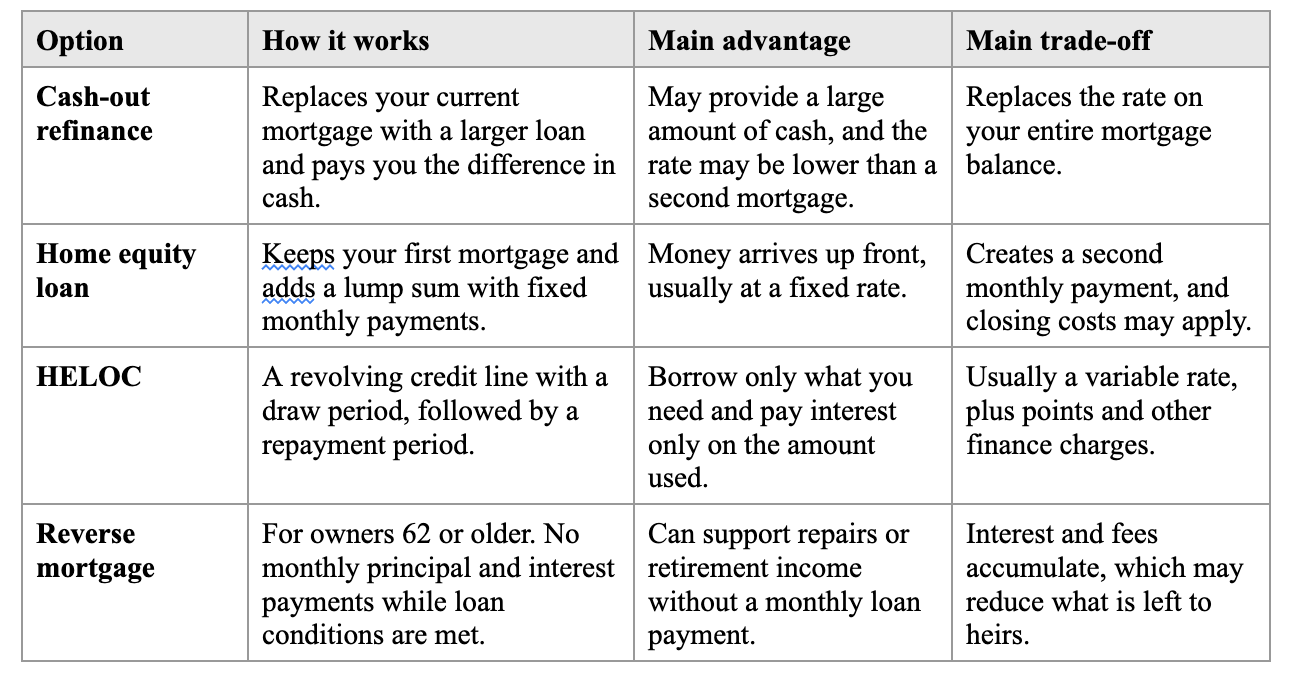
You replace your current mortgage with a larger loan and receive the difference in cash. It can provide a large amount of money, the rate may be lower than a second mortgage, and the repayment term can be shortened or lengthened.
The catch is that the new rate applies to your entire mortgage balance, not just the cash you take out. If your current rate is lower than today's rates, that deserves a hard look before you sign anything. A higher rate may also raise your monthly payment.
You keep your primary mortgage and receive a lump sum through a second one. Payments are fixed installments, and the interest rate is typically fixed too. That makes the monthly cost easy to plan around.
The trade-off is a second monthly payment. Closing costs may apply, and your home secures the loan.
A HELOC is a revolving line of credit up to a set limit, with a draw period followed by a repayment period. You withdraw funds as needed and pay interest only on the amount you use. You may be able to reuse the line, subject to the loan terms, and it can stay open with a zero balance.
Most HELOCs have a variable APR, so your payment can change. Points and other finance charges may apply, and one point equals 1% of the loan amount.
Homeowners age 62 or older may access equity while living in the home. The most common type is the FHA-insured Home Equity Conversion Mortgage, known as a HECM. HUD-approved counseling is required before the loan proceeds.
There are no monthly principal and interest payments while loan conditions are met, and the loan is generally repaid when the homeowner sells, moves out, or dies. The funds may support repairs or retirement income.
Interest and fees accumulate, which increases the balance and may reduce the inheritance left to heirs. The homeowner must still pay property taxes, insurance, maintenance, and applicable property charges. If you are considering this option, I would bring your children or other family into the conversation early.
Closing costs may run 2% to 5% of the new loan amount. On a $500,000 loan, that is $10,000 to $25,000. Because your home secures the loan, missed payments or an inability to repay can put the home at risk of foreclosure.
Before you commit, ask each lender these questions:
What are the total closing costs, including any points?
Is the rate fixed or variable, and what could my payment be if rates rise?
What happens to the rate on my current mortgage?
What happens if I sell the home in the next few years?
If you may sell in the next few years, borrowing now means paying closing costs on a loan you will soon repay. That is the question I ask long-time Greenwich owners first. Sometimes borrowing is the right answer, and sometimes the better plan is to sell on your own timeline and keep the full proceeds.
This article is general information and not legal, tax, or financial advice. Please speak with a lender, your tax advisor, and an attorney before you decide. If you would like to talk it through, I am at 203-524-4998 or [email protected], and I will give you a straight answer on what each choice means for your home.
Yes. Both are second mortgages, so your primary mortgage stays in place. The combined mortgage debt typically cannot exceed 80% of your home's appraised value.
A home equity loan pays you a lump sum up front with fixed monthly payments, usually at a fixed rate. A HELOC is a revolving line of credit you draw from as needed, and it usually carries a variable rate.
Homeowners age 62 or older. The most common type is the FHA-insured Home Equity Conversion Mortgage, and HUD-approved counseling is required before the loan proceeds.
Closing costs may run 2% to 5% of the new loan amount. A HELOC may also carry points and other finance charges, and one point equals 1% of the loan amount.
Because your home secures the loan, missed payments or an inability to repay can put the home at risk of foreclosure. That is why the decision deserves a careful look with a lender and your tax and legal advisors.
Source: National Association of REALTORS, Consumer Guide: Options to Pull Equity From Your Home (2026).
Last updated: November 2026
Stay up to date on the latest real estate trends.
Blog
Blog
Blog
Blog
Blog
Blog
Blog
How It Has Moved Since 2019
Blog
Blog
What Long-Time Owners Need to Know
Discover the best places to live across Greenwich
We are a dedicated group of Greenwich natives. We have a deep passion for our hometown and enjoy everything the town offers its residents from the beach front to the backcountry. That is why we don’t find you just any home, we find you the right home.
MARK PRUNER
DENA ZARRA
RUSSELL PRUNER
COMPASS
200 Greenwich Ave
3rd Fl Greenwich, CT 06830